In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often reminds buyers that getting pre-approved for a mortgage is only the beginning.Staying financially qualified

Dated: September 18 2026
Views: 0
In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often reminds buyers that getting pre-approved for a mortgage is only the beginning.
Staying financially qualified all the way to closing is just as important.
And there's one type of spending that buyers may not immediately think about when they're preparing to purchase a home: buy now, pay later plans.
Jamie gives a special shout-out to Lisa Obringer with Elite Loan Ladies for bringing attention to this topic, because it's something buyers especially those going through mortgage underwriting for the first time may easily overlook.
You've probably seen the option while shopping online:
“Pay $30 today and split the rest into installments.”
Services such as Affirm, Klarna, Afterpay, PayPal Pay Later and similar programs can make a purchase feel much smaller by dividing the cost into multiple payments.
One $25 or $30 payment may not seem significant.
But what happens when you have several of them?
A payment here. Another one there. A few purchases spread over multiple installment plans.
Those financial obligations can start adding up.
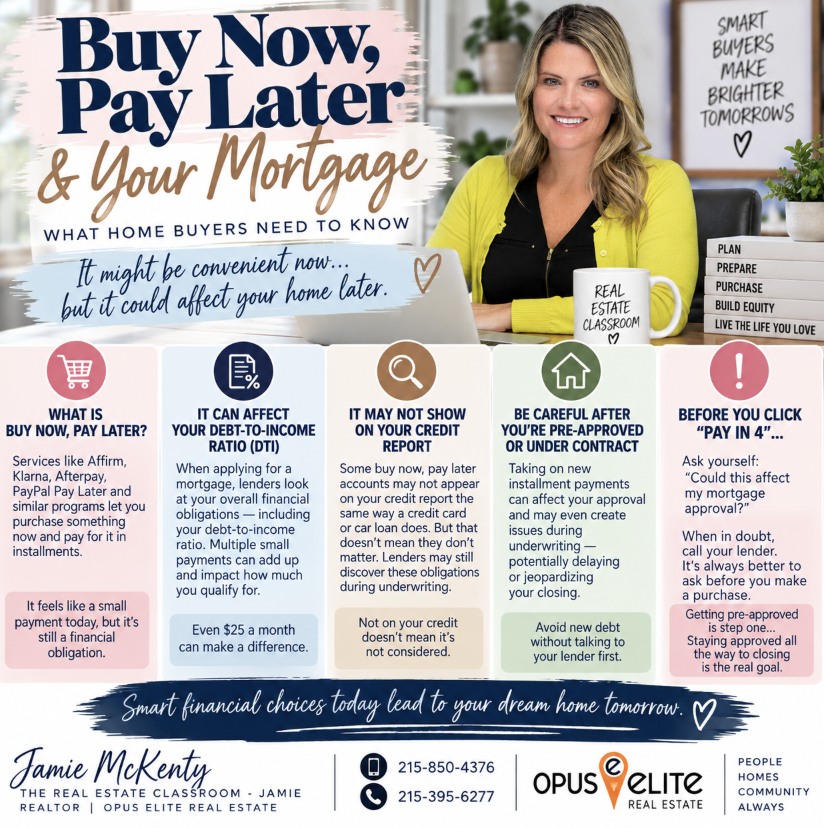
When lenders evaluate a mortgage application, they're looking at a buyer's overall financial picture including income, assets, liabilities and recurring monthly obligations.
One important calculation is the buyer's debt-to-income ratio, or DTI, which compares qualifying monthly obligations with qualifying monthly income.
That's why buyers shouldn't assume a payment is irrelevant simply because the amount seems small.
This is where buyers need to be particularly careful.
Not every financial obligation necessarily appears on a credit report in the same way. But that doesn't automatically mean a lender can ignore it.
For loans following Fannie Mae guidelines, lenders are required to consider applicable liabilities affecting a borrower's ability to make the mortgage payment and may need to verify liabilities that aren't shown on the credit report. If additional liabilities are disclosed or discovered during the mortgage process, the lender may need to recalculate the borrower's DTI and, in some circumstances, re-underwrite the loan.
That doesn't mean every BNPL purchase will automatically jeopardize a mortgage. How a particular obligation is treated can depend on the loan program, lender and specifics of the debt.
But it does mean buyers shouldn't assume, “It's not showing on my credit, so it doesn't matter.”
Jamie reminds buyers that a pre-approval isn't permission to start changing their finances.
Once you're preparing to buy, especially after you're under contract it's smart to avoid taking on new financial obligations without speaking with your lender first.
That includes financing furniture for the new house, opening new credit cards, buying a vehicle, or starting new installment plans.
You don't want to find the perfect home, negotiate an offer, complete inspections and get close to settlement only to discover that a change in your financial picture has created an underwriting issue.
Ask yourself one simple question:
“Could this affect my mortgage qualification?”
Then ask your lender.
Even if the payment seems small.
Even if you're approved instantly.
Even if you're already pre-approved for the mortgage.
A quick conversation with your lender before taking on a new obligation is much easier than trying to solve a financing problem later.
In The Real Estate Classroom - Jamie, Jamie wants buyers to understand that the decisions they make between pre-approval and closing can matter.
You don't have to stop living your life while you're buying a home—but this isn't the time to make assumptions about new debt.
And thank you again to Lisa Obringer with Elite Loan Ladies for sharing such an important reminder for buyers.
Because when you're getting ready to purchase a home:
Getting pre-approved is step one. Staying approved all the way to closing is the real goal.
Jamie McKenty
Realtor | Opus Elite Real Estate | The Real Estate Classroom - Jamie
📱 215-850-4376
☎️ Office: 215-395-6277
In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often reminds buyers that getting pre-approved for a mortgage is only the beginning.Staying financially qualified
In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often works with buyers who find a home they love only to discover that several other buyers love it too.In a
In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often explains real estate terms that can sound complicated but are actually much easier to understand once they're
In The Real Estate Classroom - Jamie, teacher and real estate agent Jamie McKenty often gets a question from buyers who have finally found the house they love:“How do I make my offer stand out
 All information is believed to be accurate but is not guaranteed. Protected by Copyright© 2026 and is owned either by the Monmouth County Association of REALTORS; or by the developers of the software, Kunversion, LLC. All rights reserved. Each office independently owned and operated.
The New Jersey Real Estate Commission requires every licensed broker or salesperson with whom you list your property to give you a copy of this notice. The purpose is to help you comply with the New Jersey Law
Against Discrimination (the "LAD) and federal laws prohibiting discrimination in the sale or rental of real property.
In New Jersey, it is illegal to discriminate against a prospective or current buyer or tenant because of race, creed, color, national origin, sex, gender identity or expression, marital status, civil union status, or source of lawful income used for mortgage or rental payments. It is also illegal to place any advertisement or make any statements or utterances that express, directly or indirectly, any limitations to offer housing based on any of those characteristics.
Show More...
 © BRIGHT, All Rights Reserved
Information Deemed Reliable But Not Guaranteed
The data relating to real estate for sale on this website appears in part through the BRIGHT Internet Data Exchange program, a voluntary cooperative exchange of
property listing data between licensed real estate brokerage firms in which
participates, and is provided by BRIGHT through a licensing agreement.
The information provided by this website is for the personal,
non-commercial use of consumers and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data last updated: September 23, 2026 1:48 PM UTC
Some properties which appear for sale on this website may no longer be available
because they are under contract, have Closed or are no longer being offered for sale.
Some real estate firms do not participate in IDX and their listings do not appear on this website. Some properties listed with participating firms do not appear on this website at the request of the seller.
Show More...
